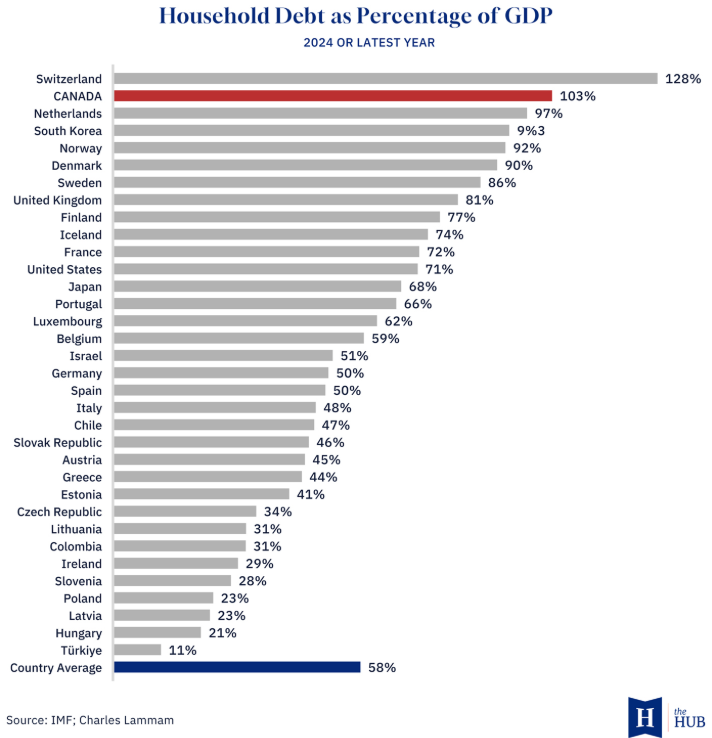
Debt is a reality a growing number of Canadians are wrestling with. Insolvency filings have kept climbing, for the 12 months ending December 2025, total insolvencies were up again year-over-year, with consumer insolvencies rising about 2.3%, according to the Office of the Superintendent of Bankruptcy. Filing rates now sit at their highest levels since before the pandemic. If you’re feeling buried under financial obligations, two of the most common ways out are debt consolidation and a consumer proposal. They work very differently, though, and picking the wrong one for your situation can cost you money or credit you didn’t need to lose. Here’s how they compare, and how to tell which is the better fit.
Reduce your credit card payments by up to 30–50%
CCC is a non-profit credit counselling agency. Talk to a trained counsellor for free to see if you qualify for a debt management program and explore other options for relief, so you can avoid bankruptcy. They’ll work with your creditors to lower your interest rates and stop late fees, then roll everything into one monthly payment, so you can be out of debt in as little as 36 months. They are not a loan company and do not lend money.
BBB Rating: A+Trustpilot 4.7/5 (6,900+ reviews)500,000+ Canadians helped$1B+ in debt eliminated
Talk to a Counsellor for Free →
Results vary by debt type, creditors, and budget. This page isn’t legal advice.
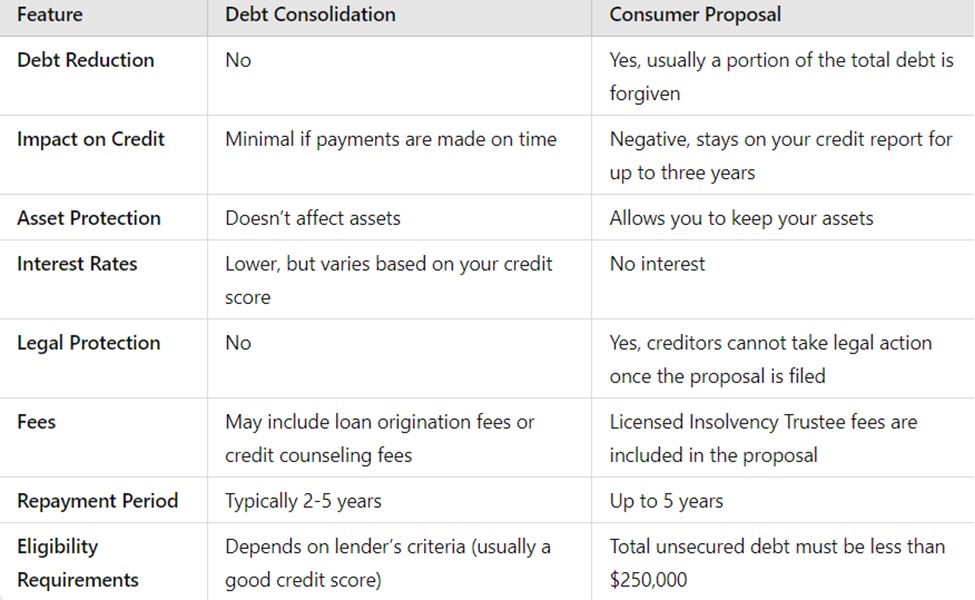
Side-by-Side: The Key Differences
| Debt Consolidation | Consumer Proposal | |
|---|---|---|
| What happens to the debt | Repaid in full, reorganized | Reduced, you repay a portion |
| Who arranges it | A bank, lender, or credit counsellor | A Licensed Insolvency Trustee only |
| Legal creditor protection | No | Yes, garnishment & calls stop |
| Credit requirement | Decent credit needed (for a loan) | For those who can’t repay in full |
| Effect on credit | Neutral to positive if managed well | R7 rating, temporary |
| Interest | Lower rate, still charged | Frozen |
| Time frame | Varies by loan term | Up to 5 years |
What Is Debt Consolidation?
Debt consolidation combines several debts into one, to make payments easier to manage and ideally lower the interest you pay. There are two main forms:
A debt consolidation loan means borrowing a single new loan to pay off your other, more expensive debts. If the new loan carries a lower rate than the debts it replaces, you save money and simplify everything into one payment. This works best for people with reasonably good credit, since that’s who qualifies for the better rates.
A debt management program (DMP) isn’t a loan. It’s a structured plan run by a non-profit credit counselling agency, which negotiates with your creditors to reduce interest and fees. You make one monthly payment to the agency, and it pays your creditors. DMPs are especially useful if you’re struggling, because they can meaningfully lower your monthly obligation, and your credit accounts are typically frozen during the program so you don’t take on more debt.
👍 Pros of debt consolidation
- One monthly payment instead of several.
- Potential interest savings if you qualify for a lower rate.
- No need to put up your home or car as collateral.
- Making steady payments can help your credit over time.
👎 Cons of debt consolidation
- You usually need decent credit to get a lower rate.
- It doesn’t reduce the principal, you still repay everything you owe.
- Some loans carry extra costs, like origination fees.
What Is a Consumer Proposal?
A consumer proposal is a legally binding agreement to settle your debt, arranged through a Licensed Insolvency Trustee (LIT), the only professional authorized to file one. The trustee negotiates with your creditors to reduce the amount you owe on unsecured debt, with payments spread over up to five years and interest frozen. It’s a formal insolvency proceeding under the Bankruptcy and Insolvency Act, sitting between a DMP and bankruptcy in severity.
👍 Pros of a consumer proposal
- You repay only a portion of your total debt, often a significant reduction.
- The moment you file, creditors can’t sue you, garnish your wages, or contact you for payment.
- Unlike bankruptcy, you keep your assets, your home, car, and other property.
- Payments are fixed for the life of the agreement, so budgeting is predictable.
👎 Cons of a consumer proposal
- It affects your credit, recorded as an R7 rating that stays on your report for three years after completion, or six years from the filing date, whichever comes first.
- It can run up to five years, a long commitment.
- You must have less than $250,000 in unsecured debt, excluding the mortgage on your primary home.
The Data: Why More Canadians Choose Proposals
The numbers tell a clear story. Consumer proposals now make up roughly 78% of all consumer insolvencies in Canada, a share that’s climbed steadily over the past several years, up from about 70% in 2021, and consumers account for nearly 97% of all insolvency filings. Canadians increasingly favour the proposal route precisely because of what the comparison above shows: it reduces the debt, freezes interest, provides legal protection, and lets people keep their assets, all without the full severity of bankruptcy. For those who genuinely can’t repay in full, it has become the debt-relief tool of choice.
That said, “most popular” doesn’t mean “right for everyone”, a proposal is a formal insolvency filing with a real credit impact, and for someone who can still repay their debt, consolidation remains the lighter-touch option.
Find relief in 3 easy steps
1Talk to a counsellor for free
Review your debts, budget, and credit to see if you qualify, and explore other options so you can avoid bankruptcy.
2Start when you’re ready
Once you enrol, they call your creditors to lower your interest rates and stop late fees.
3Get out of debt faster
Make one monthly payment and they distribute it to your creditors, debt-free in as little as 36 months.
Tip: have your balances, minimum payments, and monthly expenses handy.
Which Option Is Right for You?
Debt consolidation may be better if:
- You have a good credit score and can qualify for a low-interest loan.
- You can afford to repay your full debt but want to simplify your payments and cut interest.
- You want to avoid a significant hit to your credit.
A consumer proposal may be better if:
- You’re struggling to make minimum payments and can’t realistically repay the full amount.
- You need legal protection from creditors who are calling, suing, or garnishing wages.
- You want to keep your assets, like your home or car, while reducing what you owe.
The type of debt matters too. Consolidation suits credit cards and personal loans; a consumer proposal covers almost all unsecured debt. If your debt has outgrown what consolidation can fix, a proposal, or in the most severe cases, bankruptcy, becomes the more realistic route. Our look at bankruptcy alternatives in Canada covers the full spectrum.
Final Words
Both debt consolidation and a consumer proposal are legitimate ways to deal with overwhelming debt, they simply solve different problems. Consolidation simplifies your payments and can lower your interest while you repay everything; a consumer proposal reduces what you owe and shields you from creditors when full repayment isn’t realistic. The honest deciding factor is whether you can repay your debt in full. If you’re not sure which camp you’re in, that’s exactly the moment to talk to a professional, a non-profit credit counsellor or a Licensed Insolvency Trustee can assess your numbers, usually for free, and tell you which route genuinely fits.
Bottom line: check your options now.
If you want one place to start, CCC is a strong option. You can get a clear recommendation based on your situation, and whether the best fit is a DMP or a principal-reduction route like a consumer proposal, they can help you move forward without bouncing between random companies.
Frequently asked questions
Is a consumer proposal better than debt consolidation?
How much does a consumer proposal reduce your debt?
Does debt consolidation affect your credit score?
How long does a consumer proposal stay on your credit report?
Can I do a consumer proposal with more than $250,000 in debt?
Mohammed Saqib has a Masters Degree from Wilfrid Laurier University in Waterloo. He has a robust background in accounting and finance. Mohammed started his career three years ago working as an investment analyst at a sell-side firm. He has extensively covered publicly-listed companies using fundamental analysis as the cornerstone of his approach. Mohammed has been published on SeekingAlpha, InvesorPlace, Yahoo! Finance and others.